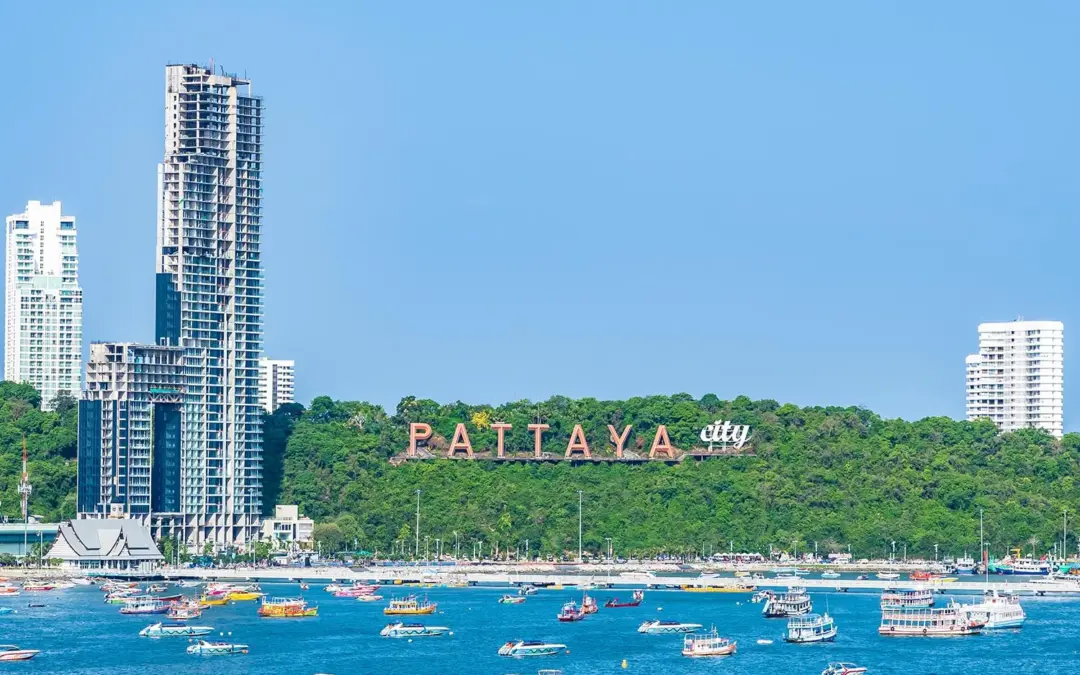
Pattaya has been a favourite retirement destination for international residents for decades, and it’s not difficult to understand why.
Warm weather, relatively affordable living costs, excellent private healthcare, international restaurants, beaches, golf courses and a large established expat community make it relatively easy to build a comfortable life here.
But retirees planning to stay in Pattaya long term eventually face an important question, on whether renting or buying a condo in Pattaya makes more sense.
There is another dimension to that decision that short-term visitors may not immediately appreciate. Having a permanent home in Thailand can make some of the practical administration associated with long-term residence easier too.
Owning a condo doesn’t give someone the right to live in Thailand indefinitely, immigration status and property ownership are entirely separate matters, but having a permanent registered address can remove some of the complications associated with repeatedly relying on landlords for address documentation.
For retirees planning to make Pattaya genuinely feel like home, that can be surprisingly valuable.
First: Does Buying a Condo Give You a Retirement Visa?
No.
Buying property in Thailand and obtaining permission to stay in Thailand are separate legal matters.
Purchasing a condominium does not automatically qualify a foreigner for a retirement visa or extension of stay.
For the commonly used retirement route, applicants generally need to be at least 50 years old and meet the applicable immigration and financial requirements.
For a retirement extension based on a Non-Immigrant visa, the commonly applied financial routes include qualifying through income of at least THB 65,000 per month, maintaining the required funds in a Thai bank account, typically THB 800,000, subject to Immigration’s rules about how long those funds must remain in the account or meeting the applicable combination requirements.
The exact requirements depend upon the immigration route being used and can change, so retirees should always check the current requirements before applying.
What owning a condo can provide is something different: a permanent Thai address and considerably more control over the paperwork associated with proving where you live.
The Advantages of Buying a Condo in Pattaya for Retirement
1. Foreigners Can Own Condominiums Freehold
One of the attractions of condominium ownership in Thailand is that qualifying foreign nationals can legally own a condo in their own name.
This is known as foreign freehold ownership.
Foreign ownership within a registered condominium is limited by Thailand’s foreign ownership quota, so the particular unit must qualify for foreign freehold registration.
For a retiree who expects Pattaya to remain home for many years, freehold ownership can provide a degree of permanence that renting cannot.
There is no landlord and no lease renewal every year. Subject to Thai law and the condominium’s regulations, the owner can renovate, sell or transfer the property and potentially leave it as part of their estate.
Anyone considering buying should understand the difference between foreign freehold, Thai quota and leasehold before committing to a property.
2. Owning Your Home Can Make Address Administration Easier
This is an advantage that is easily overlooked until someone has lived in Thailand for a while.
Long-term foreign residents regularly encounter situations where they need to provide evidence of their Thai address.
Immigration procedures can also involve Thailand’s TM30 residence notification system.
Under Section 38 of the Immigration Act, the housemaster, property owner or possessor of a residence accommodating a foreign national is responsible for notifying Immigration of the foreigner’s residence in accordance with the applicable rules.
For renters, this can sometimes mean depending on a landlord, property manager or agent to complete the required notification and provide the necessary supporting documents.
Most responsible landlords handle this without difficulty. But when they don’t, it can become the foreign resident’s problem when they subsequently need to deal with Immigration.
Owning your own condo gives you much greater control.
As the owner or possessor of your residence, you can deal with the relevant address administration yourself rather than hoping somebody else has filed the necessary information correctly.
That does not mean condo owners are exempt from TM30 requirements. It means they are in a much better position to manage their own compliance.
For someone living in Thailand throughout retirement, that independence can be worth considerably more than it initially sounds.
3. Condo Ownership Can Help Establish a More Permanent Paper Trail in Thailand
Foreign condo owners may also be able to apply to have their residence recorded in a yellow house registration book, commonly called a yellow tabien baan.
This is the house registration book used for foreign residents who qualify to be registered at a Thai address; it is different from the blue house registration book normally associated with Thai nationals and certain other eligible residents.
Owning a condo does not mean a yellow book is issued automatically, and documentary requirements can vary between the relevant district offices.
However, ownership gives a foreign retiree a permanent property address under their own control, rather than having to obtain a landlord’s cooperation to establish residence at a rented property.
A yellow book isn’t a visa and it doesn’t replace Immigration requirements. But it can become useful supporting evidence of a person’s established address in Thailand when dealing with government and administrative matters.
For a retiree who expects to spend the next decade or more in Thailand, gradually establishing this sort of local documentation can make life more straightforward.
4. No Monthly Rent
The most obvious financial advantage is that once the property has been purchased, there is no monthly landlord payment.
For retirees living on pensions, investments or savings, removing rent from the monthly budget can make expenditure more predictable.
There will still be costs.
Owners need to budget for condominium common-area fees, utilities, maintenance, insurance and occasional repairs.
But there is no landlord deciding to increase the rent or sell the property and ask the tenant to leave.
For someone expecting to spend 15 or 20 years in Pattaya, that stability can be attractive.
5. Pattaya Has Condos Across a Huge Range of Budgets
One of Pattaya’s advantages is the sheer variety of its condominium market.
There are relatively inexpensive studios and one-bedroom apartments, large units in established buildings, modern resort developments and luxury beachfront residences.
Retirees can therefore decide how much of their capital they actually want to commit to their home.
That is an important distinction.
The question isn’t necessarily:
“What’s the best condo I can afford?”
A better retirement-planning question may be:
“What condo gives me the lifestyle I want while leaving enough of my capital available for the rest of my retirement?”
That could produce a very different answer.
6. Condos Can Be Easier to Manage Than Houses
A well-managed condominium can be particularly suitable for retirement because responsibility for much of the external maintenance sits with the condominium rather than the individual owner.
Common-area fees typically contribute towards things such as security, lifts, swimming pools, gardens, cleaning and maintenance of shared areas.
For retirees who travel regularly, condos can also provide a useful lock-up-and-leave lifestyle.
There is no garden becoming overgrown or private swimming pool requiring attention while the owner spends several months overseas.
7. Pattaya Has Good Access to Private Healthcare
Healthcare should arguably be one of the biggest considerations when choosing where to retire.
Pattaya and the surrounding area have private hospitals, clinics, pharmacies and specialist healthcare services, while Bangkok remains accessible for more complex treatment.
That should also influence where within Pattaya someone buys.
At 55 or 60, driving 20 minutes to everything may seem insignificant.
Later in retirement, being able to reach a hospital, pharmacy, supermarket and restaurants easily can become much more important.
A spectacular sea view isn’t necessarily a good trade for everyday inconvenience.
8. You Can Adapt the Condo for Later Life
Ownership also gives retirees more freedom to make their home work for them.
Subject to condominium regulations, bathrooms, kitchens, flooring and interiors can be renovated.
That means a home can gradually be adapted with things such as walk-in showers, non-slip flooring, grab rails and better lighting without needing a landlord’s permission.
A retiree buying at 60 should therefore consider whether the same property could still work comfortably at 75 or 80.
The Disadvantages of Buying a Condo in Pattaya for Retirement
1. Your Money Becomes Tied Up in Property
This is probably the biggest financial argument against buying.
A condo might be an asset, but it isn’t cash.
Someone retiring with substantial savings needs to consider how much money will remain liquid after purchasing a property.
Unexpected healthcare costs, family emergencies, exchange-rate movements or simply changing plans can all create a need for accessible funds.
Buying a THB 10 million condo because someone technically has THB 12 million available may therefore be a very different decision from buying the same property with substantial investments and pension income remaining elsewhere.
2. A Condo May Take Time to Sell
Pattaya has a large property market and a substantial supply of condominiums.
A correctly priced unit in a desirable building may sell relatively quickly, but there is no guarantee.
Retirees should therefore avoid treating their property as though it were instantly accessible capital.
If health or family circumstances suddenly require someone to return to their home country, ending a rental contract will generally be considerably easier than selling a condo.
3. Ownership Doesn’t Eliminate Housing Costs
There may be no rent, but there are still common-area management fees.
Buildings can also require sinking-fund contributions or special payments for significant repairs.
A luxury development with enormous swimming pools, gardens, gyms and extensive facilities may cost substantially more to operate than a simpler condominium.
Retirees should therefore ask for the actual annual ownership costs, not simply look at the purchase price.
4. Building Management Can Make or Break the Experience
For a retirement property, the quality of the condominium’s management is arguably as important as the unit itself.
A well-managed older building with healthy finances, maintained lifts and sensible reserves may provide a far better retirement home than a spectacular newer development with poor management.
Before buying, purchasers should investigate common-fee collection, sinking funds, planned major works, lift maintenance and the general financial condition of the condominium juristic person.
5. Not Every Pattaya Condo Is Suitable for Retirement
A beautiful property can still be the wrong retirement property.
A hillside development may have wonderful views but be impractical without a car.
A duplex may look impressive but become difficult if mobility declines.
A central location might be convenient during the day but noisy at night.
Retirees should therefore think beyond the immediate viewing and ask:
Could I live here comfortably if I stopped driving?
Can I get a taxi easily?
Is there reliable lift access?
Can I walk to a supermarket?
How far away is the nearest hospital?
Is the shower accessible?
Is the building quiet at night?
Those questions may ultimately matter much more than whether the building has an infinity pool.
New or Older Condo: Which Is Better for Retirement?
New developments generally provide contemporary interiors, impressive facilities and potentially lower maintenance requirements during the early years.
Older Pattaya condominiums, however, can offer considerably more space for the money.
Some established developments have exceptionally large units that would be prohibitively expensive to reproduce in newer projects.
Age itself isn’t necessarily the problem.
Building condition and management matter more.
A properly maintained 25-year-old condominium may be a considerably safer purchase than a poorly managed development built five years ago.
Where in Pattaya Is Best for Retirees?
Different parts of Greater Pattaya suit very different retirement lifestyles.
Central Pattaya offers excellent access to shopping, restaurants, hospitals and entertainment but can be busy.
Jomtien remains particularly popular with retirees because it combines beach access with markets, restaurants, supermarkets and a well-established foreign community.
Pratumnak provides a more residential atmosphere between Pattaya and Jomtien.
Wongamat and North Pattaya include a number of higher-end developments while remaining relatively close to the city.
Further south, Na Jomtien and Bang Saray can provide a quieter coastal lifestyle, although transport becomes a more important consideration.
Anyone seriously considering buying a condo in Pattaya should therefore compare neighbourhoods as carefully as individual properties. A good retirement location is one that works for ordinary Tuesday mornings, not just one that looks impressive during a holiday.
Should Retirees Rent Before Buying?
For someone who has never actually lived in Pattaya, probably.
Renting for six or twelve months gives a prospective retiree time to understand how the city really works.
Someone who assumed they would love Central Pattaya may discover they prefer Jomtien. Someone dreaming about a peaceful condo further south may discover they would rather be able to walk to shops and restaurants.
It also gives newcomers time to understand Thai immigration, banking, healthcare and property ownership before committing substantial capital.
Once someone is confident that Pattaya really is where they want to spend their retirement, buying becomes a much more informed decision.
Freehold or Leasehold?
Foreign retirees should also understand what they’re actually purchasing.
A qualifying foreign freehold condo can be registered in the foreign buyer’s name and does not have a predetermined expiry date.
A leasehold condo is different. The buyer acquires the right to use the property for a defined period rather than permanent ownership.
Leasehold can sometimes be substantially cheaper.
For a retiree who wants somewhere to live for the next 20 or 30 years and isn’t concerned about leaving the property to heirs, that can potentially be attractive.
But the remaining lease term and contractual arrangements need to be checked carefully.
A newly registered 30-year lease and an existing lease with 12 years remaining should not be valued as though they are the same thing.
The Retirement Visa and Property Decision Should Be Planned Together
Buying a condo and obtaining a retirement visa are legally separate decisions, but from a practical perspective it makes sense to plan them together.
A retiree needs to consider:
Where will I live?
How will I demonstrate my address?
Who will deal with TM30 reporting?
What documentation will I need for Immigration?
How will I satisfy the financial requirements for my retirement extension?
How much capital can I sensibly put into property while still maintaining the required cash reserves?
That final question is particularly important.
Someone relying on the THB 800,000 bank-deposit method for their retirement extension needs to factor those funds into their financial planning rather than putting every available baht into a property purchase.
Property ownership should complement a retirement plan, not leave the owner asset-rich but short of the liquid funds needed for immigration requirements and everyday life.
So, Is Buying a Condo in Pattaya a Good Idea for Retirees?
For many people, yes.
A foreign freehold condominium can provide something particularly valuable in retirement: a permanent home in Thailand that is genuinely your own.
There is no landlord deciding whether the lease will be renewed. The property can be adapted to suit changing needs. Address administration can be kept under the owner’s control, and eligible owners can investigate establishing more permanent local documentation such as a yellow house registration book.
But ownership isn’t automatically better than renting.
Buying ties up capital. Properties can take time to sell. Common-area fees continue indefinitely, and the wrong building or location can become inconvenient later in life.
For someone new to Thailand, renting first can be the sensible choice.
For someone who already knows Pattaya well, has a secure immigration and financial plan and expects to remain for many years, buying can provide both financial predictability and a much stronger sense of permanence.
Perhaps the best test is not simply:
“Is this a good investment?”
Instead ask:
“Would I be happy living here for the next 10, 20 or 30 years and does buying it make the rest of my retirement simpler?”